Guides › Private lending
Selling a House That Needs Major Repairs: The 2026 Complete Guide
Selling a house that needs major repairs? Learn how to calculate your net profit, avoid costly renovations, and maximize walk-away cash in this 2026 guide.
Spending $20,000 on a new roof or structural stabilization often feels like a requirement for a sale, but in the 2026 market, it might actually be the fastest way to lose equity. You're likely staring at a mounting list of deferred maintenance while worrying that retail buyers will walk away or demand massive credits after the inspection. It's a valid concern; with 30-year mortgage rates hovering around 6.95%, today’s buyers have very little margin for post-closing renovations. When you're selling a house that needs major repairs, the decision to fix or fold isn't about aesthetics; it's a cold, hard math problem.
We understand the stress of managing contractors and the fear of being lowballed by opportunistic investors. This guide provides a clear financial roadmap to help you evaluate your property’s condition and calculate the actual return on investment for specific renovations. You'll learn how to identify which defects kill a retail deal and which ones you can safely ignore. We're going to compare your exit strategies side-by-side so you can maximize your walk-away cash without the headache of a traditional, drawn-out listing process.
Key Takeaways
- Distinguish between simple cosmetic updates and major structural failures like foundation issues or roof leaks that can derail traditional financing.
- Learn how to calculate your "Net Walk-Away" cash by comparing After Repair Value (ARV) against the cost of renovations.
- Discover why selling a house that needs major repairs to a direct cash buyer is often more profitable than a traditional listing when structural integrity is compromised.
- Master the legal necessity of full disclosure and professional inspections to avoid post-sale litigation and ensure a smooth transaction.
- Identify the specific scenarios where a professional cash acquisition provides the speed and certainty needed to exit a distressed asset without the friction of contractors.
Table of Contents
- Evaluating the Severity: What Defines "Major Repairs" in Today’s Market?
- The Financial Crossroads: Comparing "As-Is" Sales vs. Strategic Renovations
- Three Proven Strategies for Selling a Distressed Property
- How to Sell a Fixer-Upper: A Step-by-Step Execution Plan
- Choosing Your Partner: Why KC Home Offers is the Strategic Choice
Evaluating the Severity: What Defines "Major Repairs" in Today’s Market?
Selling a house that needs major repairs isn't just about finding a buyer; it's about finding a lender willing to fund the deal. While a dated kitchen is a preference issue, a cracked foundation is a structural liability. A distressed property is a residence in such significant physical or financial disrepair that its market value falls substantially below local comparables. Distinguishing between these categories is the first step in protecting your equity.
The Red Flags: Repairs That Stop a Traditional Sale
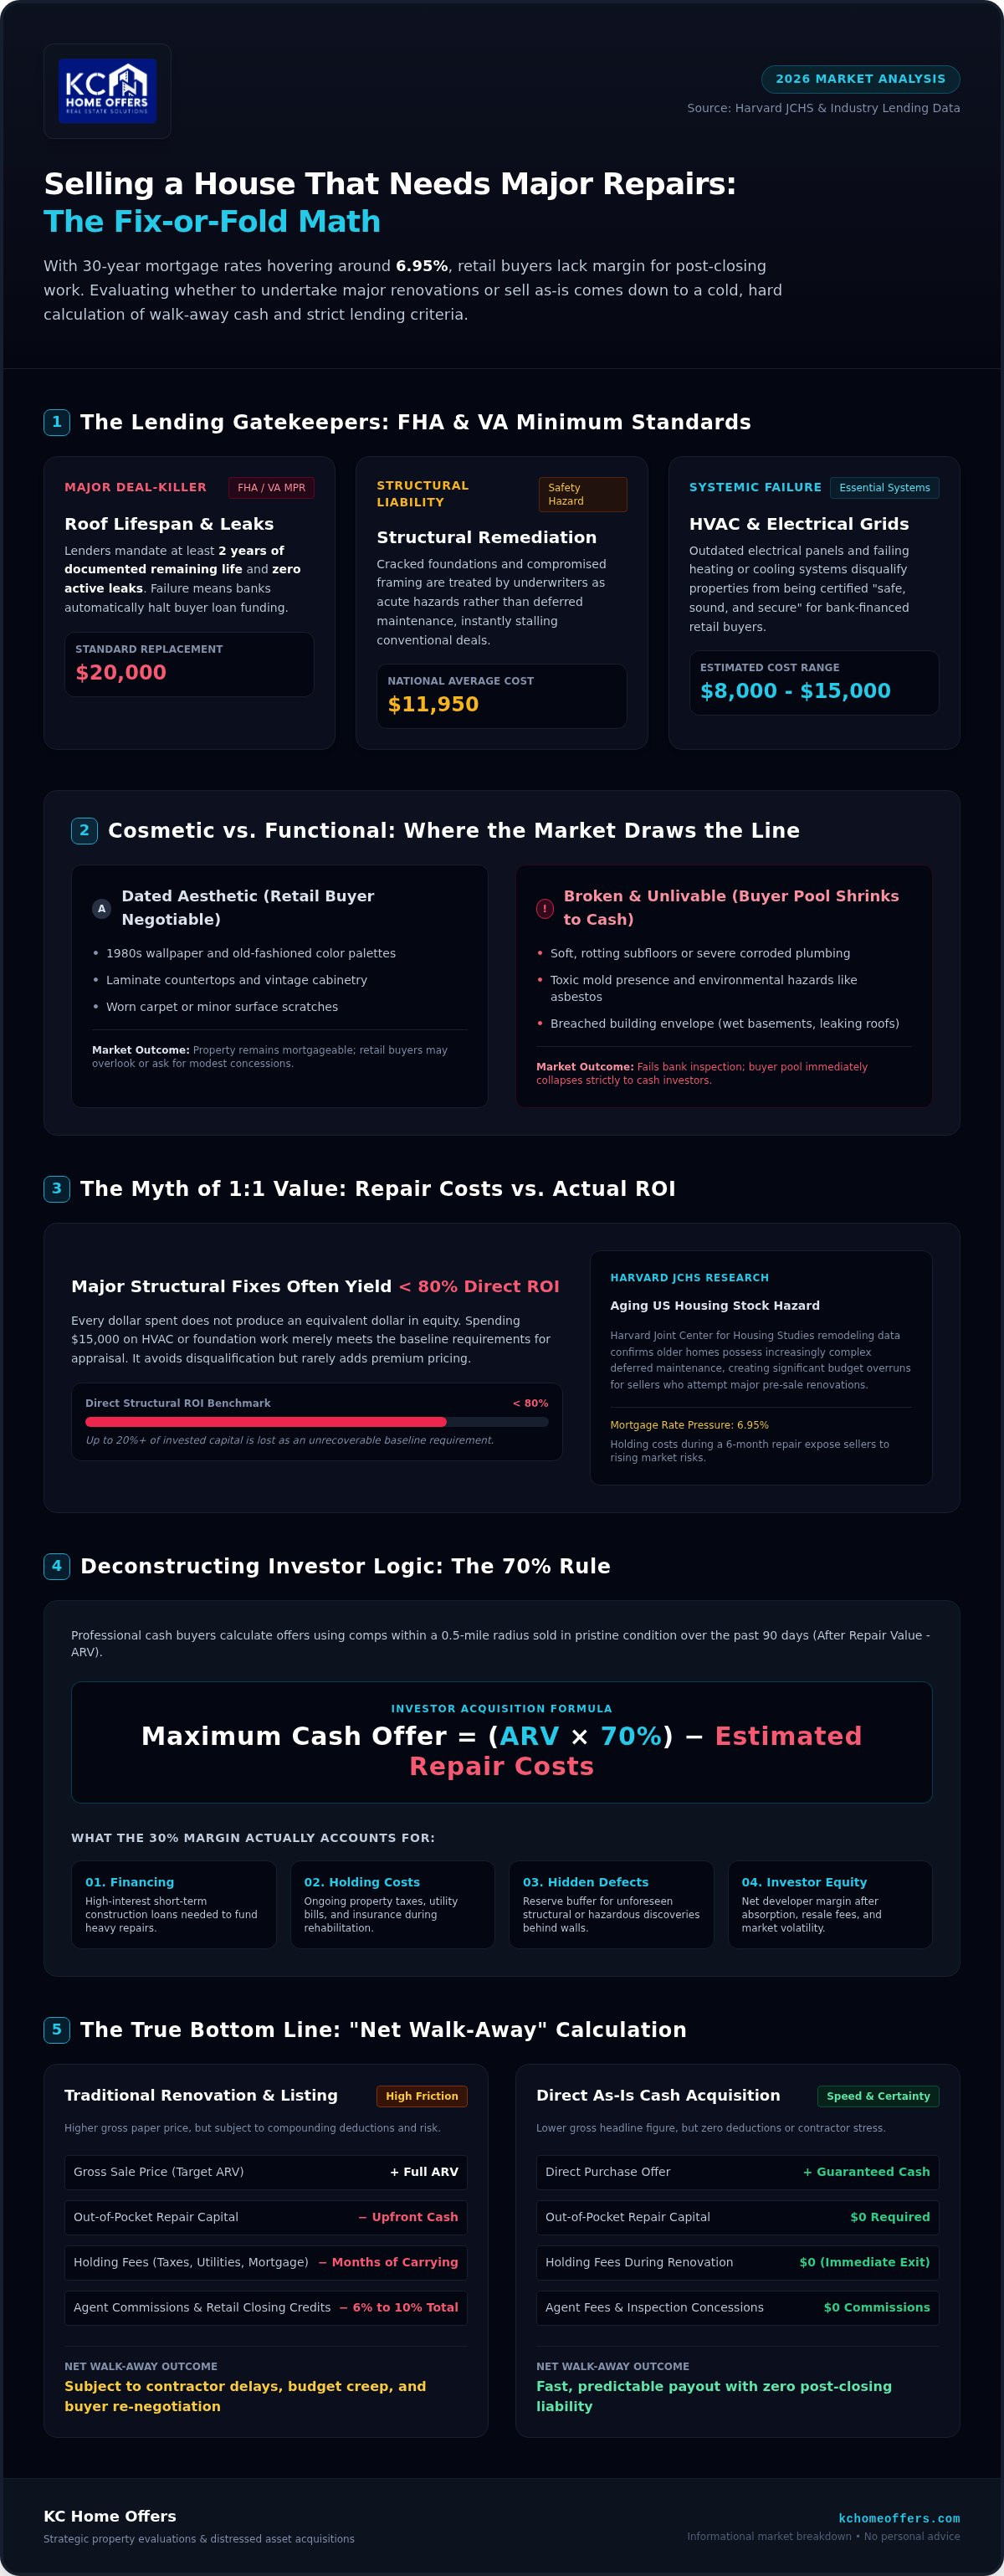
Most retail buyers rely on FHA or VA loans. These programs have strict Minimum Property Requirements (MPR) that dictate whether a bank will issue a mortgage. For instance, a roof must have at least two years of documented remaining life and zero active leaks. If it doesn't meet this standard, the lender won't release the funds. Major structural remediation, which averages $11,950 nationally, often kills a sale before it starts. Banks view these as safety hazards rather than simple maintenance. Systemic failures like outdated electrical grids or failing HVAC units, which cost between $8,000 and $15,000 to replace, are immediate deal-breakers. They won't gamble on a property that isn't safe, sound, and secure.
Cosmetic vs. Functional: Where to Draw the Line
Dated means the wallpaper is from 1982. Broken means the floor is soft or the plumbing is corroded. Retail buyers can often overlook the former, but they usually lack the surplus cash to fix the latter. Many fixer-upper properties linger on the market because sellers miscalculate the livability factor. If the home isn't livable, your pool of buyers shrinks to cash investors almost instantly.
If your budget is tight, focus on "envelope" repairs first. A dry basement and a solid roof protect the asset from further decline. Cosmetic updates like new carpet or fresh paint won't matter if the buyer's inspector finds toxic mold or environmental hazards like asbestos. Selling a house that needs major repairs requires a clear-eyed assessment of what is a want versus a need for mortgage approval. Prioritize the skeletons in the closet before you worry about the curb appeal.
The Financial Crossroads: Comparing "As-Is" Sales vs. Strategic Renovations
Deciding between a full renovation and an immediate exit is a high-stakes calculation. Most homeowners focus on the potential sale price, but the only figure that truly impacts your future is the "Net Walk-Away" cash. This is the amount remaining after you subtract repair costs, holding fees, agent commissions, and closing credits from the final price. When you're selling a house that needs major repairs, the delta between its current condition and its After Repair Value (ARV) determines your best path forward.
Understanding ARV: The Key to Investor Logic
ARV represents the estimated market value of your property once it is fully renovated to modern standards. To find this, look at "comparables", which are homes within a half-mile radius that sold in the last 90 days in pristine condition. Professional real estate investors typically follow the 70% Rule. They multiply the ARV by 0.70 and subtract the estimated repair costs to arrive at an offer. This 30% margin isn't just profit; it covers high-interest construction loans, property taxes, insurance, and the risk of discovering hidden defects once walls are opened. According to the Harvard Joint Center for Housing Studies remodeling research, the aging housing stock in the U.S. requires increasingly complex maintenance, which often leads to significant budget overruns for inexperienced DIYers.
ROI of Major Repairs: Which Fixes Actually Pay Off?
It's a common misconception that every dollar spent on repairs returns a dollar in value. Major structural work like foundation stabilization or a full roof replacement often yields less than an 80% direct ROI. You might spend $15,000 on a new HVAC system only to bring the home up to the baseline requirement for an FHA appraisal. You haven't increased the value; you've simply made it eligible for retail buyers.
Over-improving is another trap. Installing high-end quartz counters in a neighborhood where laminate is the standard won't net you a premium. Additionally, consider the cost of delay. In the 2026 market, with mortgage rates at 6.95%, the time it takes to manage a six-month renovation could expose you to price drops or rising inventory levels. Selling a house that needs major repairs as-is removes the risk of contractor ghosting and keeps your capital liquid. If you want a transparent look at your property's current value without the renovation stress, requesting a direct cash offer can provide the financial clarity you need to move forward.
Three Proven Strategies for Selling a Distressed Property
Choosing your exit path is a strategic business decision. You have three primary routes to consider when selling a house that needs major repairs: listing it on the open market, selling directly to a cash buyer, or leveraging investment capital to fix it yourself. Each path carries different risks and rewards depending on your timeline and available liquid capital.
Listing on the Open Market: Pros and Cons
This route is generally best for homes with minor to moderate issues. However, the risk of high Days on Market (DOM) is a significant factor. In the 2026 market, inventory for move-in ready homes remains lean at 2.6 months of supply, but distressed properties often linger past 60 days. This creates a "stale" listing that invites lowball offers. You'll also face the hurdle of the inspection contingency. Retail buyers often use the inspection report to renegotiate the price or demand repairs that you might not have the funds to complete. Transparency is your only tool here. Disclose everything upfront to minimize surprises that could kill the deal during the escrow period.
The Cash Offer Advantage: Speed and Certainty
For houses with structural or systemic failures, a professional cash buyer is the most efficient choice. This path eliminates bank appraisals and mortgage approvals entirely. You're selling based on the legal definition of 'as-is' contracts, meaning you don't have to clean, haul junk, or perform a single repair. If you need immediate liquidity to move on to your next chapter, you can Sell My House Fast and close in as little as 7-14 days. This certainty removes the friction of the traditional market and guarantees a specific walk-away date.
Financing the Fix: Using Investment Loans
The third option is the "Fix and Fund" approach. If you have the appetite for a project but lack the capital, you can use specialized Fix and Flip Funding to renovate the property and capture the full equity yourself. This strategy allows you to leverage short-term capital to maximize long-term gains. It isn't for everyone. You should only choose this if you're comfortable managing contractors and strict timelines. If you can handle the oversight, this path turns a distressed asset into a high-value retail listing, allowing you to scale your net worth rather than just walking away from the property in its current state.
How to Sell a Fixer-Upper: A Step-by-Step Execution Plan
Executing a sale on a distressed asset requires a tactical approach to protect your legal and financial interests. When selling a house that needs major repairs, you can't rely on the same strategies used for move-in ready homes. You need a clear execution plan that prioritizes transparency and bottom-line results.
Step 1: Get a Professional Inspection. You must know the "skeletons" in the closet before a buyer does. Spending a few hundred dollars on an inspection allows you to document the exact state of the foundation, roof, and electrical systems. This prevents the shock of a $25,000 repair demand during the escrow period.
Step 2: Disclose Everything. Honesty isn't just a moral choice; it's a legal necessity. Disclosing material facts protects you from future lawsuits. Even if you sell "as-is", you must reveal known defects like toxic mold or structural instability.
Step 3: Secure Your Property. Distressed homes are often vacant, making them targets for squatters or vandalism. Ensure all windows are locked and consider a basic security system to prevent further damage that could lower your valuation.
Step 4: Source Multiple Offers. Compare a traditional listing through an agent against a bid from Direct Home Buyers. You want to see how the market reacts to the property's current condition versus a guaranteed fast exit.
Step 5: Review the Net Sheet. Focus on the bottom line. A high retail offer often comes with "hair" on the deal, such as repair credits or seller-paid closing costs. A net sheet reveals exactly what you'll walk away with after all expenses are paid.
The Legal Side: Disclosures and Liability
The "As-Is" clause is often misunderstood. It disclaims implied warranties regarding the home's condition, but it does not exempt you from state-specific disclosure requirements. Hiding a major defect like a cracked foundation can lead to costly litigation years after the sale. If you're unsure if a defect is "material," it's always safer to disclose it. This transparency builds trust with professional Real Estate Investors who are accustomed to handling these issues.
Marketing the Potential, Not the Problem
Marketing a fixer-upper requires selling a vision. Use architectural renderings or virtual staging to show what the home could look like after a renovation. Target your messaging specifically toward flippers or landlords who have the capital to fund the work. Highlight the "Investor Opportunity" by focusing on the property's After Repair Value (ARV) rather than its current flaws. If you want to skip the marketing phase and move straight to a closing, contact our cash home buyers today for a transparent, non-contingent offer.
Choosing Your Partner: Why KC Home Offers is the Strategic Choice
KC Home Offers LLC operates as more than just a service provider; we act as a strategic ally in a market that often penalizes deferred maintenance. When you're selling a house that needs major repairs, you need a partner who understands the underlying asset value rather than one who gets spooked by a dated electrical panel or foundation cracks. We provide a dual-path solution that prioritizes your financial health, whether you need an immediate exit or the capital to maximize your equity. Our reputation is built on being "straight shooters" who value transparency and follow through on every commitment.
Direct Buying Power: A Fast Exit Strategy
Our acquisition process is designed to remove the friction that typically kills distressed property deals. Traditional retail buyers often get stuck in underwriting for 45 to 60 days, only for the lender to deny the loan due to property condition. We bypass this entire bottleneck. As direct home buyers, we use our own capital to fund acquisitions, which means we don't need bank approvals or appraisals. This allows us to close deals in as little as 7 to 14 days. You won't deal with bait-and-switch offers or hidden fees at the closing table. We provide a clear, non-contingent path to liquidity for homeowners in a bind.
Specialized Financing for the Ambitious Seller
We recognize that some homeowners want to capture the full market upside themselves. If you have the ambition to manage a renovation but lack the liquid cash, we provide the specialized financing to make it happen. Our Hard Money Loans allow you to fund major repairs without the red tape of traditional banking. This bridge capital helps you move from "distressed seller" to "real estate investor" by unlocking the property's After Repair Value. It's a faster, more professional way to scale your net worth.
For those looking to build long-term wealth, our DSCR Loans provide a way to renovate and then transition into a long-term rental strategy. We evaluate the property based on its rental income potential rather than just your personal debt-to-income ratio. This flexibility is why KC Home Offers LLC is the strategic choice for those selling a house that needs major repairs. We don't just buy houses; we provide the financial architecture for your next move. Our commitment to results ensures that you walk away with the maximum possible cash in the shortest timeframe.
Secure Your Financial Future with a Strategic Exit
Selling a house that needs major repairs doesn't have to be a source of financial friction. You've learned how to identify the structural deal-breakers that stall traditional sales and how to calculate the After Repair Value to protect your equity. Whether you choose a non-contingent cash sale or decide to leverage specialized funding to renovate, your decision should be grounded in the bottom-line math of the 2026 market. Success in distressed real estate depends on choosing a path that minimizes holding costs and maximizes your final net proceeds.
KC Home Offers provides the professional partnership you need to navigate these complex property deals with confidence. We specialize in high-growth real estate strategies, offering transparent, asset-based lending and direct home buying with no hidden fees. You don't have to manage the stress of contractors or the uncertainty of the open market alone. Our team acts as a high-integrity facilitator to ensure you move forward with momentum and clear financial results. Our expertise in distressed asset valuation provides the certainty you need to scale your ventures or simply walk away with the cash you deserve.
Get a Fair Cash Offer or Explore Funding for Your Repairs Today. You've got the roadmap; now it's time to take the next step toward a successful and stress-free sale.
Frequently Asked Questions
Can I sell a house that needs a new roof or foundation?
Yes, you can sell a property with structural defects, but it typically disqualifies retail buyers using traditional financing. FHA and VA lenders require a roof to have at least two years of remaining life and a stable foundation to approve a loan. When selling a house that needs major repairs like these, your most effective route is often a direct cash buyer who can overlook these issues and close without bank inspections.
Is it worth fixing a house before selling it to an investor?
In most cases, it is not financially beneficial to perform repairs before selling to an investor. Professional buyers calculate their offers based on the After Repair Value (ARV) and use their own specialized crews to handle renovations at a lower cost than a typical homeowner. Since major structural work often yields less than an 80% return on investment, you risk spending more on the project than you'll recover in the final sale price.
How much do cash buyers typically pay for houses that need major repairs?
Professional investors generally follow the 70% Rule to determine their offer price. They take the estimated value of the home once fully renovated and multiply it by 0.70, then subtract the anticipated cost of repairs. This formula accounts for their holding costs, financing, and the risk of hidden defects. When selling a house that needs major repairs, this approach provides you with a transparent, "as-is" price that avoids the uncertainty of the retail market.
What happens if I don’t disclose major repairs when selling my house?
Failing to disclose material defects can lead to significant legal liability and expensive lawsuits long after the closing date. Even if you use an "as-is" contract, state laws generally require you to reveal known issues like foundation cracks, toxic mold, or environmental hazards. Honesty is the only way to ensure a clean break from the property. Transparent disclosure protects your equity and prevents future claims of fraud or breach of contract from the buyer.
Can I get a mortgage for a house that needs significant work?
Standard 30-year fixed mortgages, which currently average around 6.95%, are usually reserved for habitable homes that meet minimum property standards. If a house has major safety or structural issues, traditional lenders will often deny the application. Buyers looking at distressed properties typically utilize specialized products like FHA 203(k) renovation loans or private investment capital, such as Fix & Flip loans, to fund both the acquisition and the necessary remediation work.
How do I calculate the After Repair Value (ARV) of my home?
To calculate ARV, you must analyze "comparables" in your immediate area. Look for homes within a half-mile radius that have sold in the last 90 days and are in pristine, fully renovated condition. The average sales price of these updated properties represents your home's potential value after all repairs are completed. This benchmark is essential for determining whether it is more profitable to renovate the property yourself or sell it in its current condition.
What is the fastest way to sell a distressed property in 2026?
The quickest method is selling directly to a cash home buyer. While traditional listings in the current market average 36 days on market plus another 45 days for mortgage underwriting, a cash transaction bypasses these hurdles. Since there are no bank appraisals or repair requirements, you can often move from an initial offer to a full closing in 7 to 14 days. This provides immediate liquidity and removes the stress of managing contractors.
Should I use a real estate agent to sell a fixer-upper?
An agent can be helpful if the house only needs minor cosmetic updates that appeal to DIY retail buyers. However, for properties with severe structural or systemic damage, agents often struggle to find buyers who can secure financing. In these scenarios, working directly with real estate investors is often more efficient. This path allows you to avoid paying agent commissions and prevents the deal from collapsing when a traditional buyer's lender rejects the property condition.
Frequently asked
ROI of Major Repairs: Which Fixes Actually Pay Off?
It's a common misconception that every dollar spent on repairs returns a dollar in value. Major structural work like foundation stabilization or a full roof replacement often yields less than an 80% direct ROI. You might spend $15,000 on a new HVAC system only to bring the home up to the baseline requirement for an FHA appraisal. You haven't increased the value; you've simply made it eligible for retail buyers. Over-improving is another trap. Installing high-end quartz counters in a neighborhood where laminate is the standard won't net you a premium. Additionally, consider the cost of delay. In the 2026 market, with mortgage rates at 6.95%, the time it takes to manage a six-month renovation could expose you to price drops or rising inventory levels. Selling a house that needs major repairs as-is removes the risk of contractor ghosting and keeps your capital liquid. If you want a transparent look at your property's current value without the renovation stress, requesting a direct cash offer can provide the financial clarity you need to move forward. Choosing your exit path is a strategic business decision. You have three primary routes to consider when selling a house that needs major repairs: listing it on the open market, selling directly to a cash buyer, or leveraging investment capital to fix it yourself. Each path carries different risks and rewards depending on your timeline and available liquid capital.
Can I sell a house that needs a new roof or foundation?
Yes, you can sell a property with structural defects, but it typically disqualifies retail buyers using traditional financing. FHA and VA lenders require a roof to have at least two years of remaining life and a stable foundation to approve a loan. When selling a house that needs major repairs like these, your most effective route is often a direct cash buyer who can overlook these issues and close without bank inspections.
Is it worth fixing a house before selling it to an investor?
In most cases, it is not financially beneficial to perform repairs before selling to an investor. Professional buyers calculate their offers based on the After Repair Value (ARV) and use their own specialized crews to handle renovations at a lower cost than a typical homeowner. Since major structural work often yields less than an 80% return on investment, you risk spending more on the project than you'll recover in the final sale price.
How much do cash buyers typically pay for houses that need major repairs?
Professional investors generally follow the 70% Rule to determine their offer price. They take the estimated value of the home once fully renovated and multiply it by 0.70, then subtract the anticipated cost of repairs. This formula accounts for their holding costs, financing, and the risk of hidden defects. When selling a house that needs major repairs, this approach provides you with a transparent, "as-is" price that avoids the uncertainty of the retail market.
What happens if I don’t disclose major repairs when selling my house?
Failing to disclose material defects can lead to significant legal liability and expensive lawsuits long after the closing date. Even if you use an "as-is" contract, state laws generally require you to reveal known issues like foundation cracks, toxic mold, or environmental hazards. Honesty is the only way to ensure a clean break from the property. Transparent disclosure protects your equity and prevents future claims of fraud or breach of contract from the buyer.
Can I get a mortgage for a house that needs significant work?
Standard 30-year fixed mortgages, which currently average around 6.95%, are usually reserved for habitable homes that meet minimum property standards. If a house has major safety or structural issues, traditional lenders will often deny the application. Buyers looking at distressed properties typically utilize specialized products like FHA 203(k) renovation loans or private investment capital, such as Fix & Flip loans, to fund both the acquisition and the necessary remediation work.
How do I calculate the After Repair Value (ARV) of my home?
To calculate ARV, you must analyze "comparables" in your immediate area. Look for homes within a half-mile radius that have sold in the last 90 days and are in pristine, fully renovated condition. The average sales price of these updated properties represents your home's potential value after all repairs are completed. This benchmark is essential for determining whether it is more profitable to renovate the property yourself or sell it in its current condition.
What is the fastest way to sell a distressed property in 2026?
The quickest method is selling directly to a cash home buyer. While traditional listings in the current market average 36 days on market plus another 45 days for mortgage underwriting, a cash transaction bypasses these hurdles. Since there are no bank appraisals or repair requirements, you can often move from an initial offer to a full closing in 7 to 14 days. This provides immediate liquidity and removes the stress of managing contractors.
Should I use a real estate agent to sell a fixer-upper?
An agent can be helpful if the house only needs minor cosmetic updates that appeal to DIY retail buyers. However, for properties with severe structural or systemic damage, agents often struggle to find buyers who can secure financing. In these scenarios, working directly with real estate investors is often more efficient. This path allows you to avoid paying agent commissions and prevents the deal from collapsing when a traditional buyer's lender rejects the property condition.
Need financing on a deal like this?
DSCR, fix & flip and new construction loans, underwritten on the deal rather than your tax returns. Soft credit pull only.
Apply in 5 minutes