Guides › Private lending
How Hard Money Loans Work: 2026 Investor Guide
Discover how do hard money loans work to close deals in days. Our 2026 guide shows investors how to leverage property assets for fast, competitive financing.
In a 2026 real estate market where inventory remains tight, speed is no longer just a benefit; it is the only currency that matters. If you've ever lost a lucrative distressed property to a cash buyer while waiting for a bank's underwriting department to wake up, you know that traditional financing is often the enemy of growth. Ambitious investors are increasingly bypassing the red tape of corporate banking to leverage asset-based capital instead. To compete at a high level, you must understand exactly how do hard money loans work to turn equity into immediate action.
It's frustrating to watch a perfect fix and flip opportunity slip away because of a low credit score or a property's current condition. We believe your ability to execute a deal should be valued more than a bureaucratic checklist. This guide will show you how to master the mechanics of hard money lending so you can secure financing in days rather than months. You'll learn how to use strategic leverage to increase your annual ROI, navigate the 2026 FinCEN reporting requirements, and build a clear exit strategy for short term debt. We are breaking down the transition from acquisition to long term wealth, giving you the tools to scale your portfolio with total confidence.
Key Takeaways
- Discover why asset-based lending prioritizes property value over credit scores, allowing you to secure funding for distressed assets that traditional banks often reject.
- Master the mechanics of how do hard money loans work to close competitive deals in days by using a first-position lien on your investment collateral.
- Learn how to factor upfront points and interest into your financial projections to protect your ROI and maintain healthy leverage across your portfolio.
- Identify the critical documentation needed for fast approval, including how a detailed Scope of Work and budget can accelerate your funding timeline.
- Develop a professional exit strategy to transition from short-term fix and flip debt into long-term DSCR loans for sustainable rental wealth.
Table of Contents
- What is a Hard Money Loan? Defining Private Asset-Based Lending
- The Mechanics: How Hard Money Loans Function in Practice
- The Financial Breakdown: Rates, Points, and ROI
- How to Qualify: The Hard Money Application Process
- Strategic Exit Plans: Scaling with KC Home Offers
What is a Hard Money Loan? Defining Private Asset-Based Lending
Hard money is a specialized form of short-term financing secured by the value of a property rather than the personal financial history of the borrower. Unlike traditional institutions that scrutinize every line of your tax returns, private lenders prioritize the collateral's potential. To understand What is a Hard Money Loan?, you have to view it as a strategic capital injection designed for rapid execution. Hard money serves as a high-velocity bridge to profitability for real estate investors who value execution over red tape.
The 2026 landscape has changed how do hard money loans work in terms of transparency. With the FinCEN Real Estate Rule that went into effect on March 1, 2026, investors using LLCs or Trusts must now file a "Real Estate Report" for residential purchases. While this ends total anonymity for cash-like transactions, the core benefit of private capital remains unchanged. The focus is on the deal's viability, not your personal debt-to-income ratio. This makes it the primary choice for "fix and flip" projects or properties that don't meet the strict habitability standards of a traditional bank.
The Core Difference: Hard Money vs. Traditional Mortgages
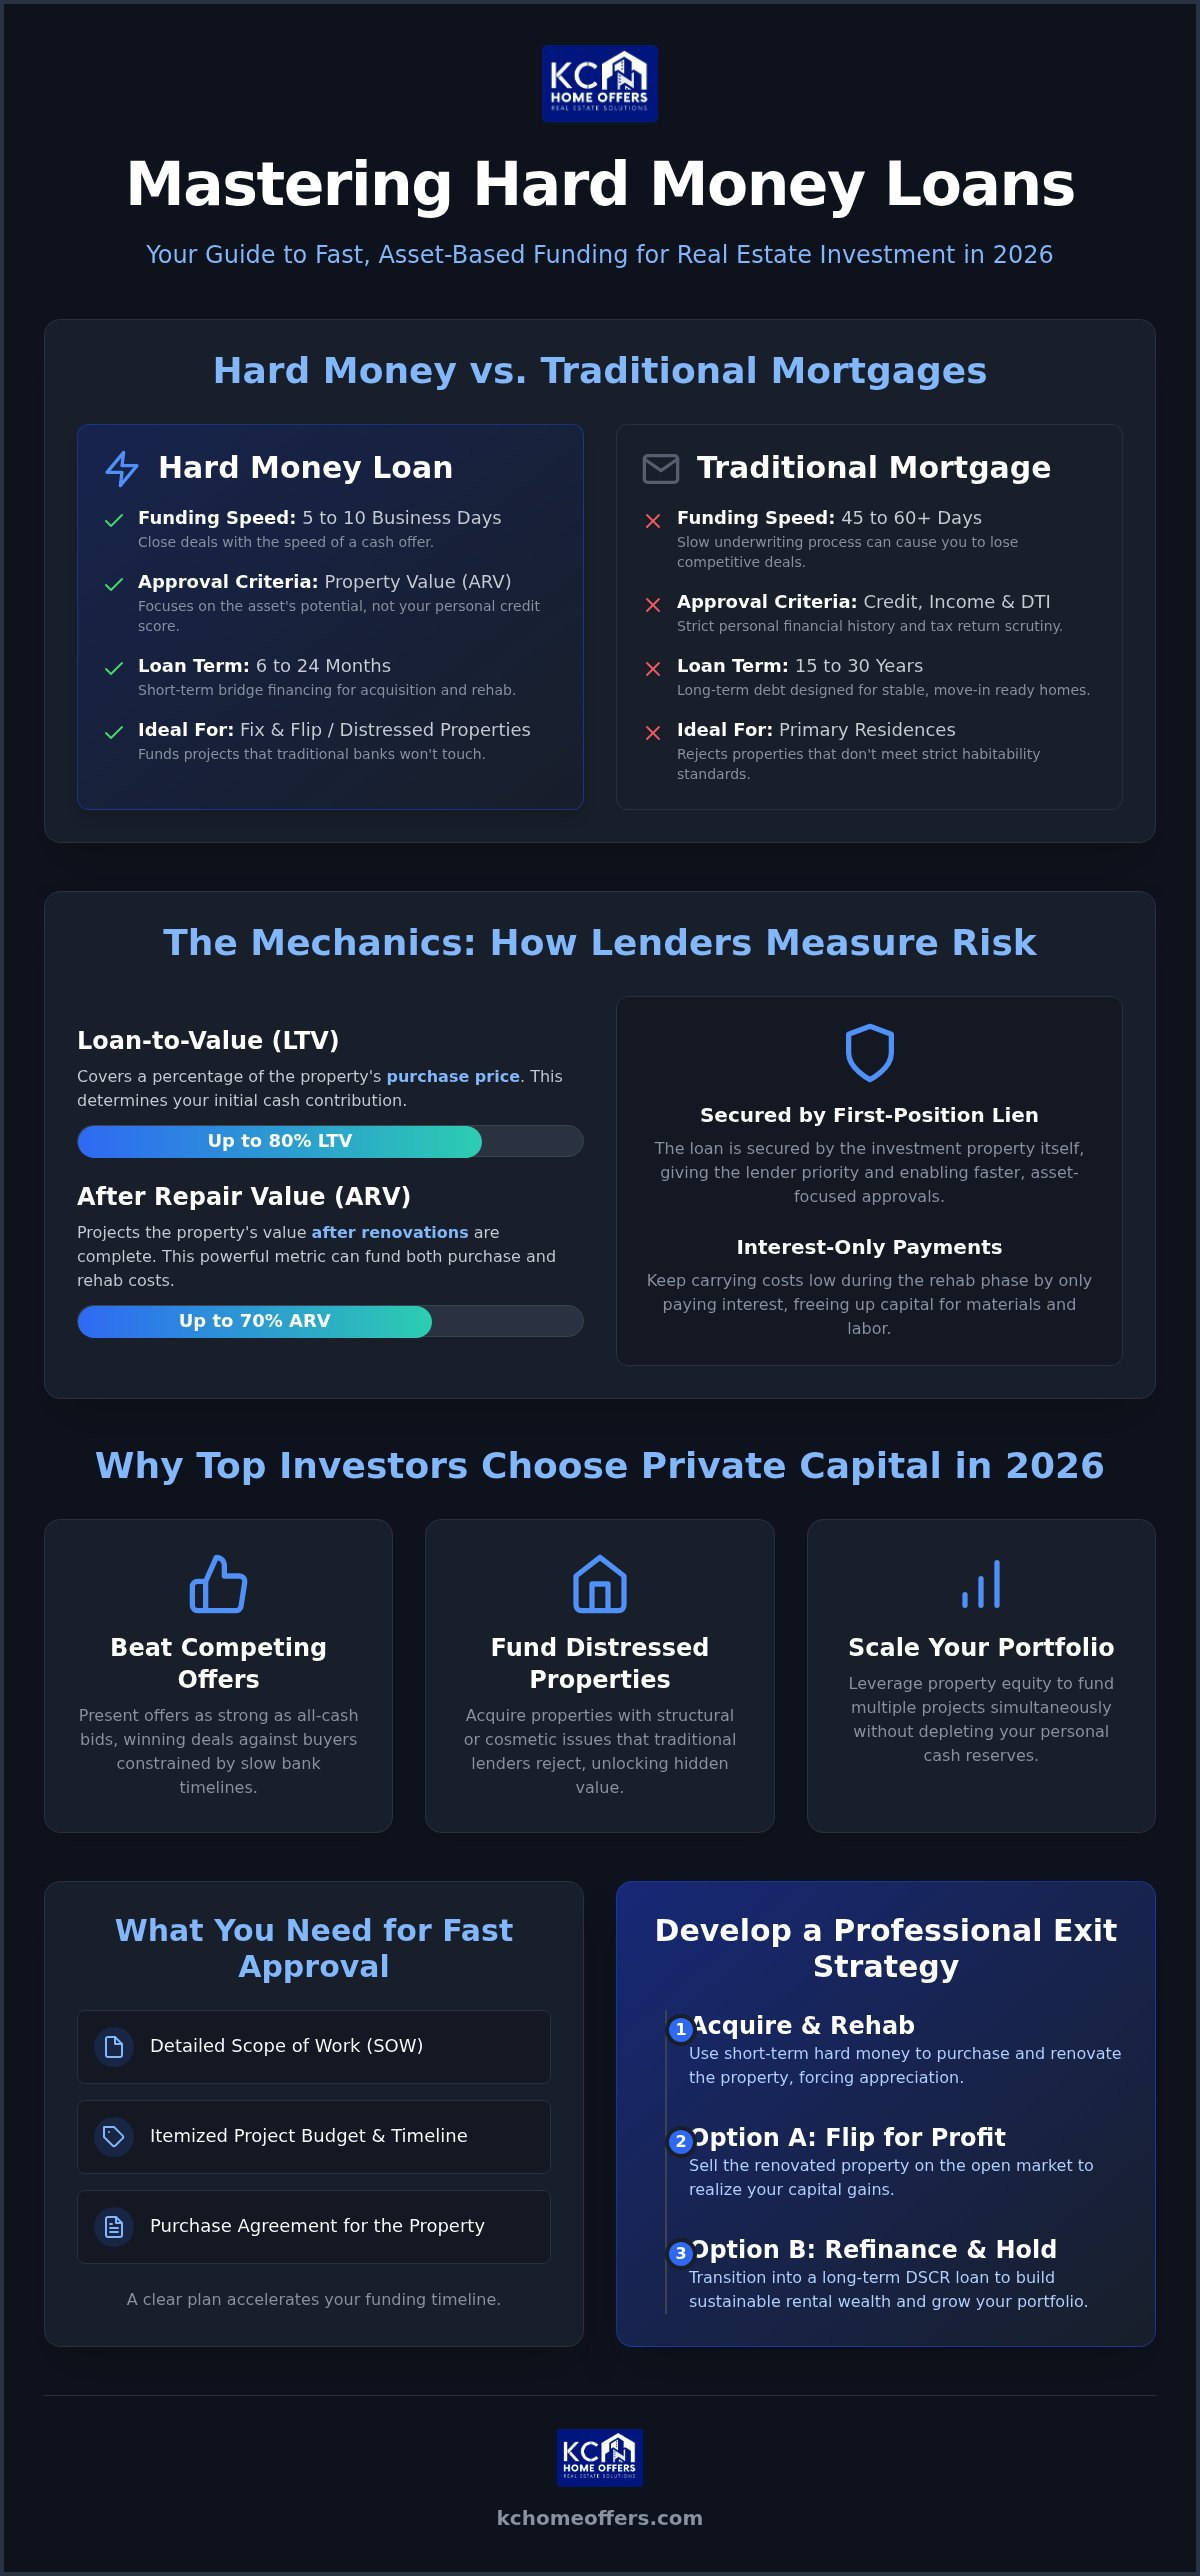
Traditional mortgages are built for long-term stability; hard money is built for immediate momentum. The most striking difference is the speed of funding. While a bank might take 45 to 60 days to navigate its committee approvals, a private lender can often fund a deal in five to ten business days. This agility is possible because the approval criteria center on the property's After Repair Value (ARV) rather than the borrower's personal income history. Additionally, the loan duration is significantly shorter. Most private capital terms range from 6 to 24 months, acting as a temporary solution until the property is sold or refinanced into a long-term DSCR Loan.
Why Investors Choose Private Capital in 2026
In a market characterized by compressed inventory and fierce competition, the ability to close quickly is your greatest competitive advantage. Investors use hard money to present offers that are as strong as all-cash bids, allowing them to beat out buyers tied to slow bank timelines. Private capital also opens doors to distressed properties that traditional lenders refuse to touch. Whether a house has structural issues or needs a complete interior overhaul, a hard money lender views these as opportunities for value-add rather than risks. By leveraging this equity, you can fund multiple projects simultaneously, scaling your portfolio without exhausting your personal cash reserves.
The Mechanics: How Hard Money Loans Function in Practice
Grasping The Mechanics: How Hard Money Loans Function involves looking at the legal and financial structure of the deal. If you want to know how do hard money loans work in a real-world scenario, you have to see them as a performance-based tool. The loan is almost always secured by a first-position lien on the investment property, giving the lender priority over any other debt. To keep your monthly carrying costs low while you're managing a job site, interest-only payments are the standard. This approach keeps your capital liquid, allowing you to reinvest it into materials and labor rather than paying down principal on a short-term debt. It's a pragmatic setup that acknowledges the property isn't generating cash flow yet. By only paying interest, you maximize your project's runway and maintain momentum.
Understanding ARV and LTV Ratios
When you ask how do hard money loans work, you have to look at how lenders measure risk. Loan-to-Value (LTV) is the standard for acquisition, usually covering a percentage of the purchase price. In 2026, many lenders offer 75% to 80% LTV. However, the real power for investors lies in After Repair Value (ARV). This metric projects what the house will be worth once the renovation is finished. Lenders often fund up to 70% of the ARV, which can sometimes cover a significant portion of both the purchase and the rehab costs. These ratios dictate how much cash you need to bring to the deal. Higher ARV projects require less out-of-pocket capital but demand a higher level of precision in your initial appraisal and budget. If you're looking to scale, using ARV-based lending is the most efficient way to preserve your personal cash reserves.
The Role of the Draw Schedule
Capital for the renovation phase is released in stages, known as draws. Your lender doesn't just hand over the full rehab budget at the start. They release funds as you hit specific construction milestones, like finishing the rough-in plumbing or installing the roof. This process protects the lender's interest and ensures the property value is actually increasing. Managing the gap between doing the work and getting the draw reimbursement is a critical skill. It's why working with an experienced hard money lender is essential. They understand the rhythm of a construction site and can process draws quickly to keep your crew moving. A smooth draw process prevents project stalls and keeps your contractors happy. If you're planning a project that requires significant structural work, our Fix & Flip Loan options are designed to match these operational realities, ensuring you have the capital when the work is done.
The Financial Breakdown: Rates, Points, and ROI
Analyzing the financial structure of a private loan requires a shift in perspective. While traditional bank rates are lower, they come with a high cost of time and restrictive terms. Interest rates in the private sector reflect the speed of the transaction and the risk profile of the asset. The true cost of hard money should be measured against the potential profit of the deal, not compared to a 30-year mortgage. When you evaluate how do hard money loans work, you'll see that points are a standard part of the closing process. One point equals one percent of the loan amount, paid upfront to cover the cost of capital and origination. Beyond these points, your closing costs will typically include appraisals, legal fees, and specific origination charges that ensure the transaction is legally sound and fully transparent. These costs are the entry price for a loan that closes in days, providing the liquidity needed to win in a competitive market.
Measuring the Cost of Opportunity
Savvy investors view interest as a line-item expense, much like lumber or labor. If paying for private capital allows you to secure a property with a $50,000 profit margin that a bank would reject, the interest is a small price for that gain. Consider the power of leverage. Using hard money might allow you to flip two houses simultaneously instead of tying up all your cash in one. This velocity of capital often proves significantly cheaper than giving away 50% of your profits to an equity partner. By maintaining control of the deal and paying a fixed cost for capital, you keep a larger share of the upside for yourself. Speed isn't just about convenience; it's about the ability to capture value before your competitors even get a callback from their loan officer.
Common Fees in a Hard Money Term Sheet
A transparent term sheet is the foundation of a good partnership. In 2026, origination fees and processing costs are standard, but you should also account for inspection fees tied to construction draws. Every time you request a release of funds for completed work, a third-party inspector typically verifies the progress. This ensures the project stays on track and the collateral remains protected. You should also check for prepayment penalties. Many private lenders, including those focused on investor success, don't charge these penalties because they want you to finish the project and move to the next deal. Understanding how do hard money loans work from a fee perspective helps you calculate your exact ROI before you ever sign the contract. It's about knowing your numbers so you can move with speed and total confidence.
How to Qualify: The Hard Money Application Process
The application process for private capital is built for speed, not bureaucracy. While a bank spends weeks analyzing your personal history, a private lender moves straight to the asset. Understanding how do hard money loans work during the qualification phase is essential for hitting tight closing deadlines. The process is streamlined into four distinct stages designed to get you from an initial offer to a funded project with minimal friction.
- Step 1: Identify the Property. You must have a specific investment property under contract. Since these are business-purpose loans, the property cannot be your primary residence.
- Step 2: Submit a Scope of Work (SOW). You maximize your chances by providing a detailed budget and renovation timeline. This document is the roadmap for your project and the basis for the loan's after-repair value.
- Step 3: Asset-Based Appraisal. The lender orders a specialized appraisal or a Broker Price Opinion (BPO). This valuation focuses on the "as-is" condition and the projected value once your SOW is completed.
- Step 4: Rapid Underwriting and Closing. Once the valuation is confirmed, underwriting moves quickly. In the current 2026 market, average closing timelines range from 5 to 10 business days, though clean files can often close in as few as 3 to 5 business days.
What Lenders Look for in a Deal
Lenders prioritize the "spread" of the deal. They want to see a healthy margin between your purchase price, the renovation costs, and the final sale price. If the numbers don't leave room for profit, the deal is considered high risk. Your experience level also plays a role. While we work with new investors, having a track record of completed projects can lead to more flexible terms. Finally, a clear exit strategy is mandatory. You must demonstrate exactly how you plan to repay the debt, whether through a traditional sale or by transitioning into a long-term DSCR Loan.
Essential Documentation for Fast Approval
To keep the momentum, you'll need your paperwork ready. This includes the executed purchase contract, your detailed renovation budget, and your entity documents. Because of the FinCEN Real Estate Rule that took effect on March 1, 2026, purchases made through an LLC or Trust now require a "Real Estate Report," so ensure your entity is in good standing and ready for disclosure. For a deeper dive into preparation, our fix and flip funding guide provides a comprehensive checklist for developers. If you have a deal ready to move, you can apply for a Fix & Flip Loan today to secure your funding before the next competitor steps in.
Strategic Exit Plans: Scaling with KC Home Offers
Hard money is a bridge, not a final destination. To succeed at scale, you need to understand that the "how" of repayment is just as important as the "how" of acquisition. When you master how do hard money loans work, you realize they are designed to be temporary, high-velocity capital. Your exit strategy should be locked in before you ever sign a term sheet. For most investors, this means either selling the asset for a profit or transitioning the debt into a more stable, long-term structure. Having a clear path forward prevents you from getting stuck with short-term interest rates once your renovation is complete.
Option A is the classic Fix and Flip. You use our capital to acquire and renovate a distressed property, then sell it to a retail buyer. This path focuses on immediate capital gains and paying off the short-term lien at closing. Option B is the BRRRR method, which allows you to build long-term wealth. Instead of selling, you refinance the property into a DSCR loan. This move allows you to hold the asset as a rental while using the property's income to cover the new mortgage. Both strategies are viable, but they require different financial preparation from the start.
Transitioning from Hard Money to DSCR
The transition from a bridge loan to permanent financing is where real rental empires are built. By using hard money to buy and renovate, you force appreciation and create equity. Once the project is complete and a tenant is in place, you can execute a cash-out refinance. This move lets you pull your initial capital back out of the deal, effectively recycling your funds for the next acquisition. This bridge-to-perm cycle is the gold standard for scaling a portfolio without constantly needing new cash injections. Our team specializes in this hand-off, ensuring your transition from a Fix & Flip Loan to long-term debt is seamless and efficient.
The KC Home Offers Advantage
We don't just provide capital; we act as a strategic ally in your growth. Our approach is built on professional integrity and a deep understanding of how do hard money loans work in the modern market. We value your time as much as you do. This is why we've optimized our approvals to match the speed of 2026 real estate dynamics. You won't find the cold, detached feel of a corporate bank here. Instead, you get transparent terms and a partner-focused environment where your success is the primary metric. We are high-integrity facilitators committed to helping you scale your ventures with confidence and clarity.
Scale Your Portfolio with High-Velocity Capital
Mastering how do hard money loans work is the first step toward outperforming the traditional market. By shifting your focus from personal credit to asset potential, you unlock the ability to secure distressed properties and close deals in days. Success in 2026 requires more than just capital; it demands a strategic partner who understands the rhythm of a renovation and the necessity of a clean exit strategy. Whether you're executing a rapid fix and flip or transitioning into long-term rental wealth, the right leverage makes all the difference. It's about maintaining momentum while others are stuck in underwriting.
We are here to act as your strategic ally through every stage of the investment cycle. At KC Home Offers, we provide Fast Approvals and Asset-Based Underwriting to keep your projects moving at the speed of the market. Our Investor-to-Investor Support ensures that you have the professional oversight needed to scale with total confidence. Don't let slow bank approvals stand between you and your next profitable deal. Secure Your Next Deal with KC Home Offers Fast Financing and take control of your financial future today. Your next project is waiting, and we're ready to help you fund it.
Frequently Asked Questions
Are hard money loans legal and safe for new investors?
Hard money loans are legal in all 50 states and represent a standard financial tool for real estate professionals. Safety for a new investor depends on transparency and working with a reputable lender that uses clear term sheets. These are asset-based loans designed for short-term investment projects rather than personal residential use. When you have a solid exit strategy and understand the costs, they are a secure way to fund deals that traditional banks won't touch.
What happens if I cannot repay my hard money loan on time?
If you miss the maturity date, you will typically face late fees or a higher default interest rate. However, most private lenders prefer a successful project over a foreclosure. If you communicate with your lender early, many can offer a loan extension for an additional fee to give you more time to finish a renovation or close a sale. If non-payment continues, the lender can initiate foreclosure to recover their capital from the property's value.
Do hard money lenders require a down payment or "skin in the game"?
Most private lenders require a down payment to ensure the investor is committed to the project's success. While some high-leverage programs may cover a large portion of the rehab costs, you should expect to bring 10% to 25% of the purchase price to the closing table. This "skin in the game" protects the lender's position and ensures that both parties are motivated to complete the project and reach a profitable exit as planned.
Can I get a hard money loan with a low credit score or no W2 income?
Yes, you can. Because these are asset-based products, your credit score and W2 income are secondary to the property's potential value. We focus on how do hard money loans work as a tool for leveraging equity rather than personal financial history. While lenders may check credit for major red flags, they don't require the strict income verification typical of traditional mortgages. This makes hard money ideal for self-employed investors or those with high-potential distressed assets.
How much do hard money loans typically cost in total fees?
Total costs include origination points, processing charges, and third-party fees like appraisals or legal costs. Points typically range from one to four percent of the loan amount and are paid at closing. You should also budget for inspection fees if your project involves a construction draw schedule. While these fees are higher than bank loans, they reflect the speed of funding and the lender's willingness to finance properties in poor condition that require significant renovation.
Is a hard money loan the same thing as a bridge loan?
They are very similar, but "bridge loan" is a broader term for any short-term debt that covers a gap in financing. A hard money loan is a specific type of bridge loan always secured by real estate and funded by private capital. In the real estate world, these terms are often used interchangeably. Both serve as a temporary bridge to get an investor from the initial acquisition and renovation phase to a final sale or a long-term refinance.
Do I need to have an LLC to apply for a hard money loan?
Most lenders require you to close the loan in the name of a business entity like an LLC or Corporation. These are business-purpose loans intended for investment rather than personal use. Closing as an entity also provides a layer of liability protection for your personal assets. Under the 2026 FinCEN regulations, your LLC will need to file a "Real Estate Report" at closing to comply with national transparency rules for residential property transactions involving private capital.
How fast can a hard money loan actually close in 2026?
In the 2026 market, a hard money loan can close in as little as 3 to 5 business days if you have a clean file and a quick appraisal. The national average typically ranges from 5 to 10 business days. This speed is a primary competitive advantage when you are trying to beat out other buyers. Understanding how do hard money loans work allows you to prepare your documentation in advance, ensuring you hit these aggressive timelines and never lose a deal.
Frequently asked
Are hard money loans legal and safe for new investors?
Hard money loans are legal in all 50 states and represent a standard financial tool for real estate professionals. Safety for a new investor depends on transparency and working with a reputable lender that uses clear term sheets. These are asset-based loans designed for short-term investment projects rather than personal residential use. When you have a solid exit strategy and understand the costs, they are a secure way to fund deals that traditional banks won't touch.
What happens if I cannot repay my hard money loan on time?
If you miss the maturity date, you will typically face late fees or a higher default interest rate. However, most private lenders prefer a successful project over a foreclosure. If you communicate with your lender early, many can offer a loan extension for an additional fee to give you more time to finish a renovation or close a sale. If non-payment continues, the lender can initiate foreclosure to recover their capital from the property's value.
Do hard money lenders require a down payment or "skin in the game"?
Most private lenders require a down payment to ensure the investor is committed to the project's success. While some high-leverage programs may cover a large portion of the rehab costs, you should expect to bring 10% to 25% of the purchase price to the closing table. This "skin in the game" protects the lender's position and ensures that both parties are motivated to complete the project and reach a profitable exit as planned.
Can I get a hard money loan with a low credit score or no W2 income?
Yes, you can. Because these are asset-based products, your credit score and W2 income are secondary to the property's potential value. We focus on how do hard money loans work as a tool for leveraging equity rather than personal financial history. While lenders may check credit for major red flags, they don't require the strict income verification typical of traditional mortgages. This makes hard money ideal for self-employed investors or those with high-potential distressed assets.
How much do hard money loans typically cost in total fees?
Total costs include origination points, processing charges, and third-party fees like appraisals or legal costs. Points typically range from one to four percent of the loan amount and are paid at closing. You should also budget for inspection fees if your project involves a construction draw schedule. While these fees are higher than bank loans, they reflect the speed of funding and the lender's willingness to finance properties in poor condition that require significant renovation.
Is a hard money loan the same thing as a bridge loan?
They are very similar, but "bridge loan" is a broader term for any short-term debt that covers a gap in financing. A hard money loan is a specific type of bridge loan always secured by real estate and funded by private capital. In the real estate world, these terms are often used interchangeably. Both serve as a temporary bridge to get an investor from the initial acquisition and renovation phase to a final sale or a long-term refinance.
Do I need to have an LLC to apply for a hard money loan?
Most lenders require you to close the loan in the name of a business entity like an LLC or Corporation. These are business-purpose loans intended for investment rather than personal use. Closing as an entity also provides a layer of liability protection for your personal assets. Under the 2026 FinCEN regulations, your LLC will need to file a "Real Estate Report" at closing to comply with national transparency rules for residential property transactions involving private capital.
How fast can a hard money loan actually close in 2026?
In the 2026 market, a hard money loan can close in as little as 3 to 5 business days if you have a clean file and a quick appraisal. The national average typically ranges from 5 to 10 business days. This speed is a primary competitive advantage when you are trying to beat out other buyers. Understanding how do hard money loans work allows you to prepare your documentation in advance, ensuring you hit these aggressive timelines and never lose a deal.
Need financing on a deal like this?
DSCR, fix & flip and new construction loans, underwritten on the deal rather than your tax returns. Soft credit pull only.
Apply in 5 minutes